
Hkma Sfc Mas Wealth Hub Regimes
HK SFC VATP & Type 1 Omnibus Uplift vs Singapore MAS PSA DPT Statutory Trust Rules
Institutional digital-asset custody and tokenized RWA distribution split sharply between Hong Kong SFC 98% cold-wallet VATP / Type 1 omnibus uplifts and Monetary Authority of Singapore PSA statutory trust rules across APAC markets.
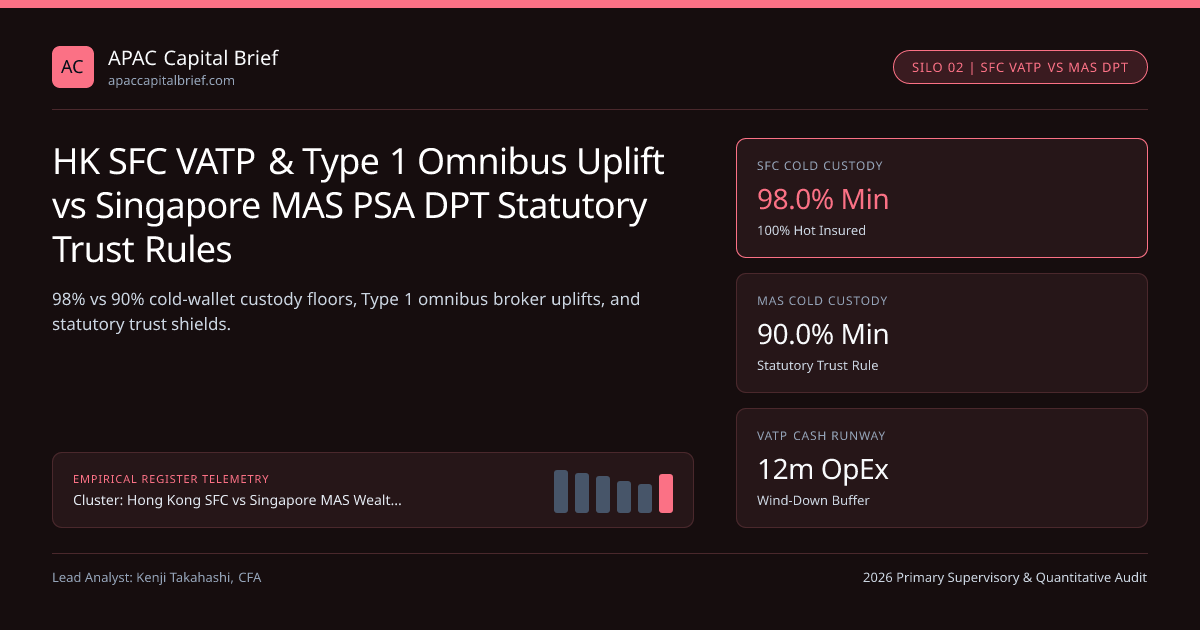
Regulated digital-asset and tokenized Real-World Asset (RWA) market infrastructure in Asia-Pacific runs on two uncompromising statutory regimes: Hong Kong's dual-ordinance Virtual Asset Trading Platform (VATP) + SFC Type 1/4/9 License Uplift architecture enforced by the Hong Kong SFC, and Singapore's amended Payment Services Act 2019 (PSA) Digital Payment Token (DPT) Custody & Statutory Trust Regulations enforced by the Monetary Authority of Singapore (MAS). While legacy offshore exchanges (such as regional crypto-native platforms or early Singapore entrants like Belfrics Singapore and BCoin SG) faced stark consolidate-or-exit choices, institutional securities brokers and private banks gained crystal-clear legal rails.
Cold-Storage Ratios, Compensation Insurance, and Statutory Trust Segregation#
Look at the forensic custody numbers mandated after FTX's collapse proved commingled omnibus wallets fatal:
- Hong Kong SFC VATP Guidelines: Licensed VATPs (operating under both the SFO for security tokens and the Anti-Money Laundering and Counter-Terrorist Financing Ordinance — Cap. 615 — for non-security tokens) must hold 98% of client virtual assets in air-gapped HSM cold storage inside Hong Kong via an Associated Entity wholly owned by the VATP (only 2% permitted in hot/online wallets!). Furthermore, following SFC's pragmatic insurance optimization, at least 50% of cold-storage assets plus 100% of the 2% hot-storage assets must be covered by third-party insurance or ring-fenced bank-guaranteed compensation reserves!
- Singapore MAS Payment Services Regulations (Statutory Trust Mandate): Major Payment Institutions (MPIs, minimum S$250,000 Base Capital + S$100,000–S$200,000 MAS security deposit) providing DPT services must hold at least 90% of customer DPTs in cold wallets, segregate customer assets on a daily-reconciled Statutory Trust basis legally insulated from MPI insolvency, and prohibit lending, staking, or rehypothecating retail customer DPTs!
The Game-Changer for Traditional Brokers: SFC "Type 1 License Uplift" Omnibus Model#
Why do traditional Hong Kong equity brokerages (such as KGI Asia and peer SFC Type 1 dealers) capture surging institutional virtual-asset and spot ETF market share without building their own matching engine? Because the SFC Joint Circular with HKMA created the Type 1 Virtual-Asset Omnibus Account Uplift:
- Instead of spending HK$50M+ applying for a standalone VATP exchange license, an existing SFC Type 1 securities broker accepts a standard Virtual Asset Dealing Licensing Condition and opens an Omnibus Client Account exclusively at an SFC-licensed VATP!
- Client fiat settles via the broker's existing Hong Kong segregated bank accounts (Cap. 571I), trades execute strictly pre-funded (zero margin/leverage extended by the broker for spot VAs), and Hong Kong stands out globally by permitting in-kind subscription and redemption on HKEX-listed Spot Bitcoin and Ether ETFs!
| Regulatory Feature | Hong Kong SFC VATP + Type 1 Uplift | Singapore MAS PSA (Major Payment Inst.) | Institutional RWA / Tokenization Edge |
|---|---|---|---|
| Cold / Hot Wallet Split | 98% Cold / 2% Hot (Keys & seeds physically in HK) | 90% Cold / 10% Hot | HK requires onshore HK FIPS 140-2 Level 3+ HSM custody |
| Retail Access & Marketing | Permitted on large-cap high-liquidity tokens (in >=2 independent indices); suitability test | Permitted without public/ATM marketing; mandatory risk-awareness assessment & no credit/leverage | SG strictly bans referral bonuses, celebrity ads & retail DPT staking/lending |
| Spot Crypto ETFs & Staking | Approved on HKEX (Cash + In-Kind creation; regulated ETH staking allowed under SFC guardrails) | Retail CIS / Spot Crypto ETFs not approved for Singapore retail listing | HK dominates exchange-listed spot VA ETF liquidity in APAC |
| Tokenized RWA & Project Guardian | HKMA Project Ensemble (wCBDC + tokenized green bonds/MMFs; SFC tokenized fund circulars) | MAS Project Guardian (40+ global banks tokenizing FX, Treasuries & wealth funds) | Both lead global institutional RWA fund tokenization! |
Expected Loss Exposure Under Cold-Hot Wallet Partition & Mandatory Insurance Coverage#
- MaxUninsuredLossPct = whot * ( 1 - Inshot ) + wcold * ( 1 - Inscold ) * ProbMultiSig_Breach
- Where (Hong Kong SFC Licensed VATP Holding US$2.0 Billion Client Virtual Assets):
- whot = 0.02 (2.0% statutory hot-wallet ceiling = US$40.0M) | Inshot = 1.00 (100% mandatory hot coverage)
- wcold = 0.98 (98.0% air-gapped HSM cold storage = US$1,960M) | Inscold = 0.50 (50% mandatory cold reserve/policy)
- Uninsured Cold Slice = 0.98 * (1 - 0.50) = 49.0% of AUM, protected by Shamir/MPC geographically sharded HK HSMs
- Worked Calculation:
- Net Client Loss Under Complete 100% Hot-Wallet Compromise = US$40.0M * (1 - 1.00) = US$0.00!
- Required Paid-Up VATP Liquid Capital Floor = max( HK$5.0M paid-up, HK$3.0M RLC + 12 Months Actual Operating Expenses! )
Watch the "12-Month Operating Expense" Cash Buffer Requirement on SFC VATPs#
Beyond standard Cap. 571N FRR liquid capital, SFC VATP Guidelines impose an extra prudential fortress: a licensed VATP must continuously hold liquid assets in Hong Kong equal to at least 12 months of its actual operating expenses (excluding depreciation/non-cash items)! For an institutional VATP burning HK$12M/month on 24/7 SOC cybersecurity, KYT blockchain analytics, and Responsible Officers, that locks HK$144 million (~US$18.5M) of unencumbered cash/T-Bills permanently on balance sheet.
Institutional Tokenized Money-Market Funds & Stablecoin Convergence#
Both hubs finalized 100% HQLA reserve-backed fiat-referenced stablecoin frameworks (HKMA Stablecoins Ordinance licensing and MAS Single-Currency Stablecoin SCS framework for SGD/G10 currencies), turning tokenized USD/HKD/SGD Treasury money-market funds into T+0 collateral across private wealth desks. Cross-check digital-asset entity registrations on our supervisory license verification portal, our Hong Kong SFC vs Singapore MAS master guide, and APAC regulatory dispatches.
Frequently asked questions
How does a traditional Hong Kong stockbroker offer crypto trading without a full VATP exchange license?
Existing SFC Type 1 securities brokers apply for a Virtual Asset Dealing License Uplift, routing pre-funded client orders exclusively through an omnibus account maintained at an SFC-licensed Virtual Asset Trading Platform.
Why did Singapore MAS ban staking and lending for retail Digital Payment Token customers?
Under MAS Payment Services Regulations effective 2024, DPT service providers cannot lend, stake, or hypothecate retail customer tokens because commingled yield programs undermine statutory trust insolvency ring-fencing.
How do Hong Kong Spot Bitcoin and Ether ETFs differ from US Spot Crypto ETFs?
Unlike initial US cash-only creation models, Hong Kong SFC approved both cash AND in-kind subscriptions and redemptions (allowing institutional holders to swap underlying BTC/ETH directly for HKEX ETF shares) plus regulated Ether ETF staking.
What is the 12-month operating expense requirement for Hong Kong SFC VATPs?
In addition to Cap. 571N Liquid Capital floors, every SFC-licensed VATP must maintain unencumbered liquid assets in Hong Kong equal to at least 12 months of its actual ongoing operating expenses to ensure orderly wind-down capacity.
Publication record
- Published
- 14 November 2026
- Updated
- 15 November 2026
- Author
- Kenji Takahashi, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Kenji Takahashi, CFA. (2026, November 14). HK SFC VATP & Type 1 Omnibus Uplift vs Singapore MAS PSA DPT Statutory Trust Rules. APAC Capital Brief. https://apaccapitalbrief.com/dispatches/sfc-vatp-type-1-uplift-vs-mas-psa-dpt-statutory-trust-rulesRelated Hkma Sfc Mas Wealth Hub Regimes & Institutional Briefings
Explore Hkma Sfc Mas Wealth Hub Regimes Hub (20) →Hkma Sfc Mas Wealth Hub Regimes
Hong Kong SFC vs Singapore MAS Wealth Hubs, Connect Rails & Licensing: 2026 APAC GuideHkma Sfc Mas Wealth Hub Regimes
Offshore CNH HIBOR Squeezes, PBoC Central Bank Bills & HKMA RMB Liquidity FacilityHkma Sfc Mas Wealth Hub Regimes
HK SFC Manager-In-Charge (MIC) & RO Rules vs Singapore MAS IAC AccountabilityHkma Sfc Mas Wealth Hub Regimes
HKEX FINI T+2 IPO Settlement & Uninterrupted Severe Weather Trading Margin RulesHkma Sfc Mas Wealth Hub Regimes
HKEX HKD-RMB Dual Counter Model: Market-Maker Stamp Duty Exemption & Southbound RMBHkma Sfc Mas Wealth Hub Regimes
MAS Notice 637 vs HKMA Banking (Capital) Rules: Basel III Final 72.5% Output Floor & Wealth RWAHkma Sfc Mas Wealth Hub Regimes
Client Money Segregation: HK SFC Cap. 571I Rules vs Singapore MAS CMS Trust AccountsHkma Sfc Mas Wealth Hub Regimes
HK SFC Type 1/4/9 FRR Liquid Capital vs Singapore MAS CMS Risk-Based Capital RulesAPAC Semiconductor AI Capex Equities
Taiwan Taipower Industrial Tariff Hikes, EUV Megawatt Intensity & Offshore Wind Fab PPAsAPAC Semiconductor AI Capex Equities
Foundry & HBM Customer Capacity Prepayments, USD Corporate Bonds & Natural FX Capex HedgingAPAC Semiconductor AI Capex Equities
JPX Growth Market JPY 10B Thresholds, METI Unsolicited Takeover Guidelines & MBO Carve-OutsAPAC Semiconductor AI Capex Equities
Nikkei 225 Price-Divisor Skew vs TOPIX Next-Generation ~1,200-Stock Float Reduction
APAC Capital Brief Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.