
APAC Semiconductor AI Capex Equities
Foundry & HBM Customer Capacity Prepayments, USD Corporate Bonds & Natural FX Capex Hedging
Zero-interest customer capacity prepayments and USD corporate bond tranches allow TSMC and SK Hynix to fund US$110B+ in AI silicon capex with natural USD revenue hedges.
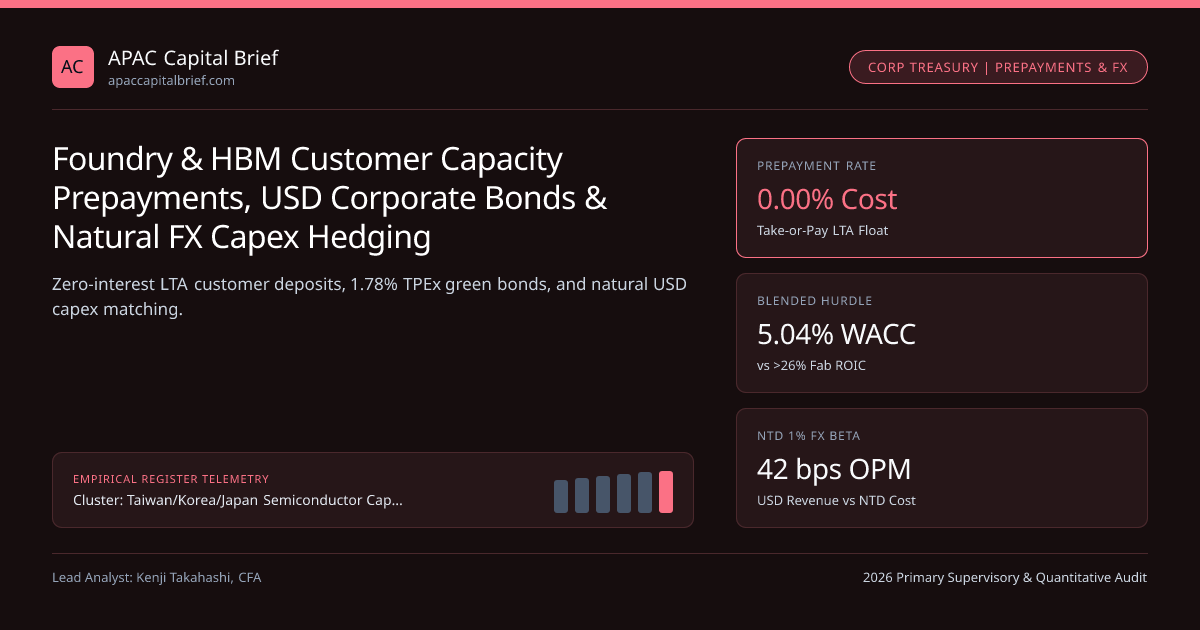
How do TSMC (US$62.0B FY2026 capex) and SK Hynix (KRW 48.0T / ~US$35B FY2026 capex) deploy nearly US$100 billion per year into fabs and EUV scanners while simultaneously lowering net debt, raising cash dividends, and maintaining single-A/AA credit ratings? Credit analysts across APAC debt desks and KGI Asia Limited point to two potent corporate-treasury weapons hidden inside IFRS balance-sheet footnotes (Temporary Receipts from Customers / Contract Liabilities): multi-billion-dollar zero-interest customer capacity prepayments and natural USD revenue-to-capex currency matching.
Zero-Interest Customer Prepayments ("Synthetic Negative-Cost Debt")#
Building a dedicated 125,000 wpm CoWoS-L packaging line or Cheongju M15X 16-high HBM4 cleanroom for a hyperscaler or GPU vendor like AMD or NVIDIA exposes the manufacturer to catastrophic stranded-asset risk if AI capex ever pauses. Consequently, leading-edge foundries and HBM leaders enforce non-cancellable long-term agreements (LTAs) backed by upfront cash prepayments:
- Accounting Mechanics (IFRS 15 Contract Liabilities): When an AI customer wires US$1.5B–US$3.0B upfront to reserve N2 wafers, CoWoS-L interposers, or 2026–2027 HBM4 stacks, the cash lands immediately in Operating Cash Flow, boosting liquidity with 0.00% interest expense and zero financial debt leverage covenants! As wafers/stacks ship over Years 2–4, the prepayment amortizes ratably as credits against invoiced shipments (or forfeits straight to profit if the customer fails to take minimum volume!).
- On TSMC's balance sheet alone, cumulative customer capacity deposits (
Temporary receipts from customers) consistently provide US$6.5 billion to US$9.5+ billion in interest-free working-capital float, while SK Hynix secured multi-trillion-won prepayments during 2024–2026 HBM3E/HBM4 contracting!
Natural FX Hedging: Why Weak NTD and Weak KRW Expand Semiconductor Margins#
Unlike Taiwanese life insurers trapped with USD assets and TWD liabilities (see Spoke 7), Northeast Asian semiconductor exporters enjoy a powerful natural USD balance-sheet match—plus positive operating leverage to local-currency depreciation:
- Top Line (~99% USD): Nearly 100% of TSMC's external wafer/CoWoS invoices and >95% of SK Hynix's HBM/DRAM export contracts are priced and settled in US Dollars.
- Capex Equipment (~78% Foreign Currency): ASML (EUR, often hedged or USD-linked), Applied Materials, Lam Research, and KLA (USD), plus Japanese WFE tools (TEL, Advantest, Disco) mean offshore USD operating cash inflows directly pay WFE equipment invoices inside offshore USD treasury accounts without ever crossing onshore TWD or KRW FX markets!
- Local Cost Base (NTD / KRW): Domestic fab engineer salaries, Taipower/KEPCO electricity bills, local construction EPC, and cash dividends are paid in NTD or KRW—meaning every 1.0% depreciation of NTD against USD expands TSMC operating margin by roughly +40 to +45 basis points!
| Financing / Treasury Channel | TSMC Treasury Execution (FSC Taiwan / SEC) | SK Hynix Treasury Execution (FSS Korea / 144A) | Strategic Credit & Equity Benefit |
|---|---|---|---|
| Customer LTA Prepayments | US$6.5B–US$9.5B non-interest temporary customer receipts | Multi-trillion KRW upfront HBM3E/HBM4 capacity deposits | Eliminates customer cancellation risk + cuts WACC by ~35–55 bps |
| Offshore USD Bond Issuance | TSMC Arizona Corp (parent-guaranteed Aa3/AA- Rule 144A notes, ~US$15B+ outstanding) | SK Hynix Rule 144A USD Green & Sustainability-Linked Bonds (Baa2/BBB+ tightening) | USD coupon & principal naturally serviced by USD export receivables! |
| Onshore Local Bond Market | NT$ corporate green bonds on Taipei Exchange (TPEx) at ~1.65%–1.90%! | Onshore KRW AA- corporate bonds at ~3.35%–3.65% | Ultra-cheap onshore NT$ debt funds Hsinchu/Kaohsiung civil construction |
| Functional vs Reporting FX | Reports in NTD; holds >US$55B+ cash/marketable USD & NTD liquidity | Reports in KRW; weak KRW generates immediate FX translation profit on USD AR | Shields free cash flow during strong-USD / Fed-higher-for-longer cycles |
Effective Weighted Average Cost of Capex Capital (WACC_Capex) With 0% Customer Prepayments & Local Green Debt#
- WACCCapex = wPrepay * (0.00%) + wLocalBond * kNTD * (1 - tc) + wUSDBond * kUSD * (1 - tc) + wOCFEquity * k_e
- Worked Incremental US$20.0B CoWoS-L & N2 Expansion Financing Blend:
- 20% Customer Capacity Prepayments (US$4.0B @ 0.00% cost)
- 20% Onshore TPEx NTD Green Bonds (US$4.0B eq. @ 1.78% pre-tax, 16% effective tax -> 1.50% after-tax)
- 15% USD Parent-Guaranteed Notes (US$3.0B @ 4.75% pre-tax -> 3.99% after-tax)
- 45% Retained Operating Cash Flow (Equity Hurdle k_e = 9.20%)
- Blended Project Hurdle Rate = (0.20 * 0%) + (0.20 * 1.50%) + (0.15 * 3.99%) + (0.45 * 9.20%)
- = 0.00% + 0.30% + 0.60% + 4.14% = 5.04% Blended Hurdle vs >26% Incremental Fab ROIC!
AI Fab Capital Stack Cost Comparison (After-Tax Annualized %)#
Credit Desk Takeaway: Watch Contract Liabilities as a 6-Quarter Leading Indicator#
Long before wafer shipments appear in quarterly revenue, equity and credit analysts read quarter-over-quarter changes in IFRS 15 Contract Liabilities and Customer Deposits: a rising balance confirms hyperscalers are locking in Year+2 CoWoS-L and HBM4 cleanrooms, whereas net amortization without replenishment signals peak capex ordering! Cross-reference TSMC US$62B CoWoS-L margins, SK Hynix KRW 48T HBM4 capex, and our Northeast Asia semiconductor & governance hub, or explore all APAC silicon dispatches.
Frequently asked questions
How are semiconductor customer capacity prepayments accounted for under IFRS?
Upfront cash prepayments enter Operating Cash Flow upon receipt and sit on the balance sheet as non-interest-bearing Contract Liabilities / Temporary Receipts from Customers, amortizing into revenue or offsetting accounts receivable as contracted wafers ship.
Why did TSMC issue billions in USD bonds via TSMC Arizona Corp if it holds over US$55B in cash?
Issuing parent-guaranteed USD notes directly out of TSMC Arizona Corp funds US fab construction in USD, creates US tax-deductible interest shields against future Arizona operating income, and avoids unnecessary cross-border cash repatriation taxes.
Why are TSMC onshore NTD corporate bond coupons so low (~1.75%–1.90%)?
Taiwan domestic banks and bond funds hold massive excess NTD savings with scarce AA+/AAA domestic corporate supply, allowing Taiwan flagship issuer to borrow 5-to-10-year NTD green bonds barely 10–20 bps over sovereign Taiwan Government Bonds.
How can equity analysts use Contract Liabilities to forecast AI semiconductor demand?
Because customers wire capacity deposits 12 to 24 months ahead of cleanroom tool installation, net additions to Contract Liabilities provide an audited balance-sheet leading indicator of 2027–2028 N2/A16 and HBM4 demand.
Publication record
- Published
- 14 November 2026
- Updated
- 15 November 2026
- Author
- Kenji Takahashi, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Kenji Takahashi, CFA. (2026, November 14). Foundry & HBM Customer Capacity Prepayments, USD Corporate Bonds & Natural FX Capex Hedging. APAC Capital Brief. https://apaccapitalbrief.com/dispatches/foundry-hbm-customer-prepayments-usd-bond-capex-hedgingRelated APAC Semiconductor AI Capex Equities & Institutional Briefings
Explore APAC Semiconductor AI Capex Equities Hub (20) →APAC Semiconductor AI Capex Equities
Northeast Asia Semiconductor AI Capex, HBM4 Supply Chains & Corporate Governance: 2026 APAC GuideAPAC Semiconductor AI Capex Equities
JPX Growth Market JPY 10B Thresholds, METI Unsolicited Takeover Guidelines & MBO Carve-OutsAPAC Semiconductor AI Capex Equities
Nikkei 225 Price-Divisor Skew vs TOPIX Next-Generation ~1,200-Stock Float ReductionAPAC Semiconductor AI Capex Equities
Taiwan NT$5.8T Retail High-Dividend ETF Crowding, Income Equalization & FSC SITCA ReformsAPAC Semiconductor AI Capex Equities
US BIS Foreign Direct Product Rule (FDPR), HBM Export Controls & APAC WFE Servicing RiskAPAC Semiconductor AI Capex Equities
TSMC US$62B FY2026 Capex & 125,000 wpm CoWoS-L Ramp: Packaged Wafer Margin MechanicsAPAC Semiconductor AI Capex Equities
SK Hynix KRW 48T HBM4 Capex & MR-MUF Yield Lead vs Samsung TC-NCF Hybrid BondingAPAC Semiconductor AI Capex Equities
TSE Prime 1.0x PBR Governance Enforcement: WACC vs ROIC Spread & JPX Name-and-ShameASIC Afsl Australian Superannuation
Australian Non-Bank RMBS Issuance, Warehouse Facility Mechanics & APRA APS 120 SecuritisationASIC Afsl Australian Superannuation
RBNZ OCR vs RBA Cash Rate Divergence: AUD/NZD Cross, BKBM–BBSW & Trans-Tasman Mortgage TransmissionASIC Afsl Australian Superannuation
Australia Mandatory AASB S2 Climate Reporting (Group 1 & 2), Scope 3 Safe Harbor & ASIC Greenwashing SuitsASIC Afsl Australian Superannuation
Australian Superannuation Decumulation Wave: Retirement Income Covenant & AUD Bond/Annuity Rotation
APAC Capital Brief Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.